Does Car Insurance Cover Tires Here is What You Need to Know
Does car insurance cover tires? The answer depends on your policy type and what caused the damage. Comprehensive coverage and collision coverage may pay for tire replacements in certain situations, but standard policies often exclude normal wear and tear. This guide breaks down exactly when your insurance provider will cover tire damage and when it won’t.
You’re driving home after a long day. You hit a big pothole. You hear a loud thump. You pull over and realize your tire is flat. Your first thought? Does car insurance cover tires? It’s a question a lot of drivers ask, and the answer isn’t as simple as yes or no.
The truth is, tire coverage depends on several factors. Your car insurance policy type, the cause of the damage, and your specific policy limits all play a role. Some drivers are surprised to learn their plan covers tire replacement. Others find out the hard way that their policy excludes it entirely.
This article breaks it all down. You’ll learn exactly when your insurance provider will pay for tire damage. You’ll also discover what’s not covered, how to file a tire damage claim, and smart tips to protect your investment. Let’s dive in.
Key Takeaways
- Tire coverage depends on your policy type: comprehensive and collision plans may cover tire damage from covered events.
- Normal wear and tear is not covered: insurance won’t pay for tires that are simply old or worn out.
- Road hazards like potholes and nails may be covered under comprehensive coverage depending on your provider.
- Filing a claim requires documentation: photos, police reports, and receipts help speed up the process.
- Your deductible matters: you’ll pay out of pocket up to your deductible amount before coverage kicks in.
- Aftermarket tires may have limits: some policies cap payouts for non-factory tires.
- Always review your policy details: understanding your policy limits prevents surprises at claim time.
📑 Table of Contents
What Does Car Insurance Cover?
Before we talk about tires specifically, it helps to understand what a standard car insurance policy covers. Most drivers carry a mix of coverage types. Each type handles different situations.
Understanding Your Policy Basics
Car insurance is not one single thing. It’s a bundle of different protections. Here are the most common types:
- Liability coverage — pays for damage you cause to others
- Comprehensive coverage — covers non-collision damage to your vehicle
- Collision coverage — pays for damage from accidents with other vehicles or objects
- Uninsured/underinsured motorist coverage — protects you when the other driver has no insurance
Most states require liability coverage by law. But comprehensive and collision are optional. They’re often part of full coverage auto insurance packages. If you want tire coverage beyond normal wear, these two types matter most.
What’s Typically Included in a Standard Policy
A basic policy focuses on liability. It pays for injuries and property damage you cause to others. It does not cover damage to your own car. That’s where comprehensive and collision come in.
Think of it this way. Liability covers the other guy. Comprehensive and collision cover you. But even then, there are rules. Your insurance provider will only pay for covered events. A fender bender? That’s collision. A stolen tire? That’s comprehensive. Normal aging? Not covered.
The key is understanding the difference between a covered event and expected maintenance. More on that below.
Does Car Insurance Cover Tire Damage?
Now let’s get to the big question. Does car insurance cover tires? The short answer is sometimes. The long answer depends on what happened to your tires.
When Tires Are Covered by Insurance
Your car insurance policy may cover tire damage in these situations:
- Accidents with other vehicles — If another car hits your vehicle and damages your tires, collision coverage usually pays for repairs.
- Vandalism or theft — If someone slashes your tires or steals them, comprehensive coverage typically kicks in.
- Weather damage — Hail, flooding, or falling tree branches can damage tires. Comprehensive coverage often applies here.
- Fire damage — If a fire damages your tires, comprehensive coverage should cover the loss.
- Civil unrest — Damage from riots or protests may fall under comprehensive coverage.
Notice a pattern? Most covered tire damage comes from events outside your control. These are sudden, unexpected incidents. That’s what comprehensive coverage is designed for.
When Tires Are Not Covered
Insurance companies draw a clear line between damage and wear. Here’s when your tire coverage likely won’t apply:
- Normal wear and tear — Tires wear out over time. That’s expected maintenance, not an insurance event.
- Poor maintenance — If you didn’t keep proper air pressure or rotate your tires, the insurer may deny the claim.
- Intentional damage — If you or someone you know caused the damage on purpose, coverage won’t apply.
- Racing or off-road use — Using your car in ways not intended can void tire coverage.
The most important thing to remember is this: insurance covers surprises. It does not cover aging. If your tires are old and worn, replacement is your responsibility.
| Situation | Covered? | Coverage Type |
|---|---|---|
| Tire slashed by vandalism | Yes | Comprehensive |
| Tire damaged in a collision | Yes | Collision |
| Tire damaged by a pothole | Maybe | Comprehensive or Collision |
| Tire worn out from use | No | Not covered |
| Tire damaged by hail | Yes | Comprehensive |
| Tire punctured by a nail on the road | Maybe | Comprehensive |
| Tire stolen | Yes | Comprehensive |
| Tire blowout from old age | No | Not covered |
As you can see from the table, the answer really depends on the cause. A road hazard like a pothole or nail falls into a gray area. Some providers treat it as a comprehensive claim. Others may classify it under collision. It varies by company and policy.
Comprehensive Coverage and Tire Damage
Comprehensive coverage is the big player when it comes to tire coverage. This type of insurance covers damage that isn’t caused by a collision. Let’s explore how it works for tires specifically.
Comprehensive coverage is sometimes called “other than collision” coverage. It protects against a wide range of non-driving incidents. Think of events like theft, fire, flooding, falling objects, and animal damage.
When it comes to tires, comprehensive coverage often applies to these scenarios:
- Vandalism — Someone deliberately damages your tires
- Theft — Your tires are stolen from your vehicle
- Weather events — Hail, ice storms, or flooding damages your tires
- Falling objects — A tree branch or debris falls on your car
- Fire — A fire damages your vehicle and tires
The Role of Your Insurance Deductible
Here’s something many drivers forget. Even when coverage applies, you still pay a portion. That’s your insurance deductible. Deductibles typically range from $250 to $1,000.
Let’s say your tire replacement cost is $800 and your deductible is $500. Your insurer pays $300. You pay $500. That’s why it’s important to weigh the cost of replacing tires against your deductible. Sometimes paying out of pocket makes more sense than filing a claim.
Expert Insight: “Many drivers don’t realize that filing a claim can raise their insurance premium,” says Sarah Mitchell, a licensed insurance advisor with over 12 years of experience. “If the tire replacement cost is close to your deductible, it might be smarter to pay for it yourself.”
Collision Coverage and Tire Damage
Collision coverage handles damage from crashes. If you hit another car, a guardrail, or a stationary object, collision coverage pays for repairs. This includes tire damage caused by accidents.
Here’s when collision coverage typically applies to tires:
- Single-car accidents — You hit a curb, a pothole, or a tree
- Multi-car accidents — Another vehicle hits you and damages your tires
- Rollover accidents — Your car flips and tires sustain damage
Pothole Damage and Insurance
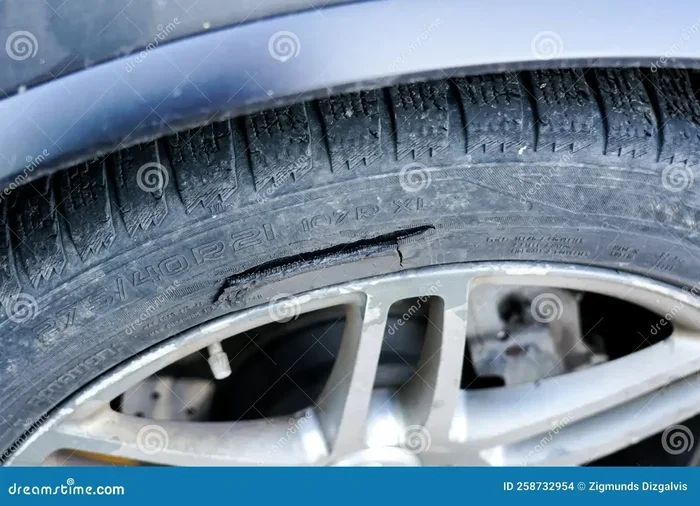
Potholes are one of the most common causes of tire damage. But coverage for pothole damage can be tricky. It depends on how the damage is classified.
If you hit a pothole and lose control, crashing into a guardrail or another car, that’s a collision claim. Your collision coverage would apply. But if you just hit a pothole and damage the tire with no other incident, it might fall under comprehensive coverage as a road hazard.
The classification matters because it determines which coverage type pays and whether your deductible applies. Always check with your insurance provider to understand how they handle pothole damage specifically.
How Much Does It Cost to Replace Tires?
Understanding tire replacement cost helps you decide whether to file a claim. Tires are not cheap. The cost varies based on several factors.
Average Tire Replacement Costs
Here’s a rough breakdown of what you might pay:
- Economy tires — $80 to $120 per tire
- Mid-range tires — $120 to $200 per tire
- Premium or performance tires — $200 to $400+ per tire
- SUV or truck tires — $150 to $500+ per tire
- Aftermarket tires — Costs vary widely based on brand and quality
For a full set of four tires, you could pay anywhere from $320 to $2,000 or more. That’s a big range. Your insurance provider will typically cover the cost up to your policy limits minus your deductible.
Factors That Affect Tire Replacement Cost
Several things influence how much you’ll pay for new tires:
- Tire size — Larger tires cost more
- Tire brand and model — Premium brands cost more
- Whether you need all four or just one — Replacing only one tire can sometimes cause handling issues
- Installation and balancing fees — These add $15 to $45 per tire
- Wheel alignment — Often recommended after tire replacement
Quick Tip: If your insurance provider replaces only one tire but the others are significantly worn, ask about matching requirements. Mismatched tires can affect handling and safety.
How to File a Tire Damage Claim
If you’ve decided to file a tire damage claim, here’s what you need to do. The process is straightforward if you’re prepared.
Step-by-Step Claim Filing Process
- Document the damage — Take clear photos of all damaged tires from multiple angles. Include close-ups of punctures, slashes, or sidewall damage.
- Get a police report if needed — For vandalism, theft, or hit-and-run incidents, file a police report. This strengthens your claim.
- Contact your insurance provider — Call your agent or use the company’s app to start the claim. Report the incident promptly.
- Get repair estimates — Visit a trusted tire shop and get a written estimate for replacement costs.
- Submit your documents — Provide your photos, police report, and estimate to the insurer.
- Wait for the adjuster’s decision — The insurer reviews your claim and determines coverage and payout amount.
- Complete the repair — Once approved, get your tires replaced and submit your receipt if required.
Common Mistakes to Avoid When Filing a Claim
- Waiting too long to report — Delays can lead to claim denial
- Not documenting properly — Poor photos or missing details weaken your case
- Admitting fault — Don’t assume you’re at fault. Let the insurer decide
- Ignoring your deductible — Know your deductible before filing
- Not reading your policy — Understanding your policy limits prevents surprises
Common Mistakes: Many drivers assume all tire damage is covered. It’s not. Normal tire wear and tear is excluded. Also, failing to maintain your tires properly can give the insurer grounds to deny your claim. Keep your tires inflated, rotate them regularly, and replace them when tread depth gets low.
Tips to Protect Your Tires and Your Wallet
Prevention is always better than dealing with a claim. Here are practical steps to keep your tires safe and avoid unexpected costs.
Regular Maintenance Habits
Taking care of your tires extends their life and reduces the risk of unexpected damage. Here’s what you should do:
- Check tire pressure monthly — Underinflated tires are more prone to blowouts and uneven wear
- Rotate tires every 5,000 to 7,500 miles — This promotes even wear across all tires
- Check wheel alignment annually — Misalignment causes uneven tire wear
- Inspect tires for visible damage — Look for bulges, cuts, or embedded objects
- Keep your tires properly balanced — Balancing prevents vibration and uneven wear
When to Consider a Tire Warranty
Some tires come with a tire warranty from the manufacturer. These warranties often cover premature wear or defects. They’re different from insurance but can save you money.
If you frequently drive on rough roads or in areas with lots of road hazards, a tire warranty or road hazard protection plan might be worth the investment. Some tire shops offer these plans at purchase time.
Smart Driving Habits
Your driving style affects tire life too. Here are a few habits that help:
- Avoid potholes when possible — Slow down and steer around them safely
- Don’t speed over curbs — This can damage tire sidewalls
- Avoid hard braking — It causes premature tread wear
- Drive smoothly — Gentle acceleration and cornering extend tire life
Expert Insight: “Drivers in areas with poor road conditions should consider higher comprehensive coverage limits,” advises James Rivera, a certified auto insurance specialist. “A small increase in your insurance premium can save hundreds of dollars if you ever need a tire replacement.”
Key Takeaways
- Comprehensive and collision coverage may cover tire damage from covered events like vandalism, theft, accidents, and weather.
- Normal tire wear and tear is never covered by any standard car insurance policy.
- Road hazards like potholes and nails may be covered, but classification varies by insurer.
- Your deductible and policy limits determine how much you actually receive from a claim.
- Filing a claim can raise your premium, so weigh the cost of repair against potential rate increases.
- Aftermarket tires and specialty tires may have different coverage limits than factory-installed tires.
- Always read your policy carefully and ask your insurance provider specific questions about tire coverage.
Conclusion
So, does car insurance cover tires? The answer is: it depends. Your comprehensive coverage and collision coverage can pay for tire damage from covered events. But normal wear and tear is always your responsibility.
The best thing you can do is understand your policy. Know what’s covered, what’s not, and what your deductible is. Review your car insurance policy annually. Ask your insurance provider specific questions about tire damage and tire puncture coverage.
Taking good care of your tires also helps. Regular maintenance, smart driving habits, and a good tire warranty can all reduce your risk. When damage does happen, knowing how to file a tire damage claim makes the process smoother and faster.
Bottom line: does car insurance cover tires — yes, in many situations. But preparation and knowledge are your best tools. Stay informed, stay proactive, and you’ll be ready for whatever the road throws at you.
Frequently Asked Questions
Does full coverage auto insurance cover tire damage?
Full coverage auto insurance typically includes both comprehensive and collision coverage. This means tire damage from accidents, vandalism, theft, and weather events is usually covered. However, normal wear and tear is still excluded. Check your specific policy for details on policy limits and exclusions.
Will my insurance pay for a flat tire caused by a pothole?
It depends on your coverage type and how the incident is classified. If the pothole damage is treated as a road hazard, comprehensive coverage may apply. If it caused a collision with another vehicle or object, collision coverage would apply. Contact your insurance provider to confirm how they handle pothole-related tire damage.
What is the cost of a tire damage claim on my premium?
Filing a claim can increase your insurance premium by 10% to 40% depending on your provider and claims history. However, some companies offer accident forgiveness. If the claim cost is close to your deductible, paying out of pocket might be the better financial choice.
Are aftermarket tires covered by car insurance?
Most standard policies cover aftermarket tires, but there may be limits. Your insurance provider typically pays the actual cash value or replacement cost up to your policy limits minus your deductible. Check your policy for specific terms about non-factory tires.
How long does a tire damage claim take to process?
Most auto insurance claims for tire damage are processed within 2 to 4 weeks. Simple claims with clear documentation can be resolved faster. Claims requiring adjuster visits or additional investigation may take longer. Prompt reporting and complete documentation speed up the process.
Do I need a police report for a tire damage claim?
It depends on the cause of damage. For vandalism, theft, or hit-and-run incidents, a police report is usually required. For single-vehicle pothole damage or wear-related issues, a police report may not be necessary. Always check with your insurance provider for their specific requirements.