Maserati Ghibli Insurance Cost What You Need to Know
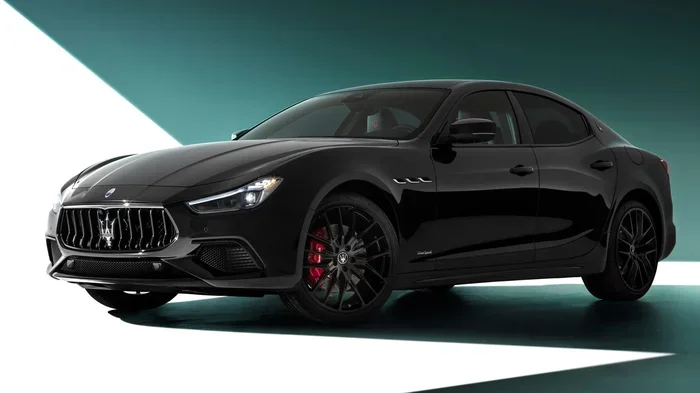
The Maserati Ghibli insurance cost is higher than most sedans because it is a luxury sports car with expensive parts and repairs. On average, owners pay between $2,000 and $4,500 per year for coverage. Your rate depends on factors like your age, driving record, location, and the Ghibli trim level you own.
Owning a Maserati Ghibli is a dream for many car lovers. The sleek design, powerful engine, and Italian craftsmanship make it one of the most desirable sports sedans on the road. But there is a side of luxury car ownership that not everyone talks about: insurance.
If you are thinking about buying a Ghibli or you already own one, you need to understand the Maserati Ghibli insurance cost. This guide breaks everything down in simple terms. We will look at why the rates are high, what affects the price, and how you can save money without sacrificing coverage.
Insurance for a luxury vehicle is not the same as insurance for a family sedan. The parts cost more. The repairs take longer. And the risk profile is completely different. By the end of this article, you will know exactly what to expect and how to get the best deal on your policy.
Key Takeaways
- High repair costs drive up the Maserati Ghibli insurance cost significantly compared to standard vehicles.
- Your personal factors like age, location, and driving history play a big role in your premium.
- Full coverage is recommended for luxury cars like the Ghibli to protect your investment.
- Shopping around and comparing quotes from multiple insurers can save you hundreds of dollars.
- Discounts are available for safe driving, bundling policies, and installing anti-theft devices.
- Newer Ghibli models tend to cost more to insure due to higher market value and advanced features.
- Working with an insurance specialist who understands luxury cars can help you find the best deal.
📑 Table of Contents
- Why Does Maserati Ghibli Insurance Cost More Than Average?
- Factors That Affect Maserati Ghibli Insurance Cost
- Average Maserati Ghibli Insurance Cost by Year
- Types of Coverage You Need for a Maserati Ghibli
- Tips to Lower Your Maserati Ghibli Insurance Cost
- Common Mistakes People Make When Insuring a Maserati Ghibli
- Expert Insights on Insuring Luxury Sports Sedans
- Key Takeaways
- Conclusion
Why Does Maserati Ghibli Insurance Cost More Than Average?
The short answer is that luxury cars cost more to insure. But the reasons go deeper than just the price tag. Let us look at the main factors that push the Maserati Ghibli insurance cost above what you would pay for a regular car.
Expensive Parts and Repairs
A Maserati Ghibli is not a mass-produced vehicle. Parts are imported from Italy and are far more costly than parts for a Toyota or Honda. If you get into an accident, the repair bills can be shocking. Insurance companies know this, and they factor it into your premium.
For example, a simple bumper repair on a Ghibli can cost three to five times more than the same repair on a mainstream car. The headlights, sensors, and body panels are all specialized. Even minor fender benders can lead to five-figure repair costs.
High Theft Risk
Luxury cars are always on the radar for thieves. The Maserati Ghibli is no exception. Its sleek look and high resale value make it a target. Insurance companies charge more to cover vehicles that have a higher chance of being stolen.
This is one reason why comprehensive coverage is so important for Ghibli owners. Without it, you would be paying out of pocket if your car was stolen or vandalized.
Performance and Speed
The Ghibli is a sports sedan. It is fast, agile, and built for driving excitement. But performance vehicles also come with higher risk. Speeding tickets are more common among sports car owners. And high-speed accidents tend to cause more damage.
Insurance companies see this as a higher likelihood of claims. That is why sports sedans like the Ghibli carry a steeper price tag on insurance than family-friendly SUVs or sedans.
Factors That Affect Maserati Ghibli Insurance Cost
Not everyone pays the same rate for Ghibli insurance. Several factors come into play. Understanding these can help you anticipate what you will pay and find ways to reduce your premium.
Your Age and Driving Experience
Young drivers pay the highest rates across the board. If you are under 25, expect to pay significantly more for Ghibli coverage. Insurance companies view younger drivers as less experienced and more likely to get into accidents.
On the flip side, if you are a mature driver with a clean record, you will qualify for much better rates. Age is one of the biggest factors in determining your car insurance premium.
Your Driving Record
A clean driving record is your best friend when it comes to insurance. If you have no speeding tickets, no accidents, and no claims, you will pay less. Even one DUI or at-fault accident can double your rates.
Insurance companies look at your history as a predictor of future behavior. The safer you drive, the lower your Maserati Ghibli insurance cost will be over time.
Your Location
Where you live matters a lot. If you live in a big city like New York or Los Angeles, your rates will be higher. Urban areas have more traffic, more accidents, and more theft.
If you live in a rural area with low crime rates, you will likely pay less. Your zip code is one of the first things an insurer checks when you get a vehicle insurance quote.
The Ghibli Trim Level and Model Year
Not all Ghiblis are the same. The base Ghibli costs less than the Ghibli S or the Ghibli Trofeo. Higher trims have more powerful engines and more features, which means higher insurance costs.
Newer models also cost more to insure because they are worth more money. A 2024 Ghibli will have a higher premium than a 2018 model. If you are shopping for a used Ghibli, keep in mind that the model year can affect your rates.
Your Credit Score
In many states, insurance companies use your credit score to help set your rates. A higher credit score usually means lower premiums. A lower score can make your luxury car insurance even more expensive.
This might seem unfair, but it is a common practice in the industry. Keeping your credit in good shape can save you real money on your Ghibli policy.
How You Use the Car
Do you drive your Ghibli every day for a long commute? Or is it a weekend car that sits in the garage most of the time? How you use the vehicle affects your rate.
Low-mileage drivers often pay less. If you can prove you only drive your Ghibli occasionally, you may qualify for a low-mileage discount. This is one of the easiest ways to bring down your auto insurance rates.
Average Maserati Ghibli Insurance Cost by Year
Now let us get into the numbers. The Maserati Ghibli insurance cost varies widely depending on the factors we just discussed. Here is a general breakdown of what you can expect.
On average, full coverage insurance for a Ghibli runs between $2,000 and $4,500 per year. That is roughly $170 to $375 per month. Compare that to a Honda Accord, which might cost $1,200 to $1,800 per year. The difference is significant.
Here is a rough estimate by model year:
- 2017-2019 Ghibli: $1,800 to $2,800 per year
- 2020-2022 Ghibli: $2,200 to $3,500 per year
- 2023-2024 Ghibli: $2,800 to $4,500 per year
These numbers are averages and can vary based on your personal situation. The best way to get an accurate number is to get quotes from multiple insurers. Never just accept the first quote you receive.
Types of Coverage You Need for a Maserati Ghibli
Not all insurance policies are created equal. When it comes to a luxury car like the Ghibli, you need the right mix of coverage to fully protect yourself and your investment.
Liability Coverage
Liability coverage pays for damage you cause to other people or their property. This is required by law in most states. For a Ghibli, it is wise to carry higher-than-minimum liability limits.
If you are at fault in an accident, the other driver’s repairs and medical bills can add up fast. Higher liability coverage protects your personal assets. This is especially important for luxury car owners who have more to lose.
Collision Coverage
Collision coverage pays for damage to your own car after an accident, regardless of who is at fault. For a Maserati Ghibli, this coverage is essential. Repair costs are too high to handle out of pocket.
Make sure your collision deductible is something you can afford. A lower deductible means higher premiums, but it also means less out-of-pocket expense if you get into a crash.
Comprehensive Coverage
Comprehensive coverage protects against non-accident damage. This includes theft, vandalism, fire, flooding, and falling objects. Given the theft risk associated with luxury cars, comprehensive coverage is a must for Ghibli owners.
Think of it this way: collision covers crashes, and comprehensive covers everything else. Together, they form the backbone of full coverage insurance for your vehicle.
Uninsured/Underinsured Motorist Coverage
This coverage kicks in when the other driver does not have enough insurance or none at all. It is surprisingly common for drivers to be uninsured. This coverage protects you when the other person cannot pay for the damage they caused.
For a high-value car like the Ghibli, this is an important safeguard. It can save you from a major financial hit after an accident that was not your fault.
Gap Insurance
If you are financing or leasing your Ghibli, gap insurance is worth considering. It covers the difference between what you owe on the loan and what the car is actually worth if it is totaled.
Luxury cars depreciate faster than you might think. Gap insurance ensures you are not stuck paying for a car that is no longer drivable. Many lenders require it, but even if they do not, it is a smart buy.
Tips to Lower Your Maserati Ghibli Insurance Cost
Insurance for a luxury car does not have to break the bank. There are several proven strategies to bring down your Maserati Ghibli insurance cost. Here are the most effective ones.
Shop Around and Compare Quotes
This is the single most important tip. Different insurers price risk differently. One company might charge you $3,000 a year while another charges $2,200 for the exact same coverage.
Use online comparison tools to get quotes from at least three or four companies. Do not just go with the first option you find. Shopping around can save you hundreds of dollars every year.
Bundle Your Policies
If you have homeowners or renters insurance, look into bundling it with your auto policy. Most insurers offer a multi-policy discount. This can reduce your overall insurance cost by 10 to 25 percent.
Bundling is an easy way to save money without giving up any coverage. It is one of the best-kept secrets in the insurance world.
Ask for Discounts
Insurance companies offer many discounts that most people do not know about. Safe driver discounts, good student discounts, and defensive driving course discounts are all common.
Some insurers also offer discounts for anti-theft devices, telematics programs, and paperless billing. Always ask your agent what discounts you qualify for. You might be leaving money on the table.
Increase Your Deductible
A higher deductible means lower monthly premiums. If you can afford to pay a $1,000 or $2,000 deductible out of pocket, you will save on your annual premium.
This is a smart trade-off for many Ghibli owners. Just make sure the deductible amount is something you can realistically handle if you ever need to file a claim.
Maintain a Clean Driving Record
Safe driving is the best long-term strategy for lowering your insurance cost. Avoid speeding tickets, accidents, and claims whenever possible.
Over time, a clean record will reward you with lower premiums. Some insurers also offer accident forgiveness programs that prevent your rates from going up after your first claim.
Consider Pay-Per-Mile Insurance
If you do not drive your Ghibli every day, pay-per-mile insurance might be a great option. This type of policy charges you based on how much you actually drive.
For people who use their luxury car as a weekend cruiser, this can lead to significant savings. Ask your insurer if they offer a pay-per-mile program.
Common Mistakes People Make When Insuring a Maserati Ghibli
Even the best intentions can lead to costly mistakes when insuring a luxury car. Here are the most common errors Ghibli owners make.
Choosing Minimum Coverage
It is tempting to go with the cheapest policy to save money. But minimum coverage often does not pay for the damage a luxury car can cause. If you total another vehicle or cause a serious accident, minimum liability limits will not be enough.
Always carry sufficient coverage for a high-value vehicle. The savings on your premium are not worth the financial risk.
Not Shopping Around
Many people just renew their policy year after year without comparing rates. The insurance market changes constantly. A company that was the cheapest last year might not be the cheapest this year.
Make it a habit to compare quotes at least once a year. You might be surprised by how much money you can save.
Ignoring the Deductible
Some people pick a deductible without thinking it through. A very low deductible means high premiums. A very high deductible means you cannot afford to pay it if you need to file a claim.
Find a deductible that fits your budget and risk tolerance. This is a key part of managing your Maserati Ghibli insurance cost over the long term.
Failing to Report Changes
If you move, get married, change jobs, or add another driver to your policy, you need to update your insurer. These life changes can affect your rates, and failing to report them can void your coverage.
Keep your insurer informed at all times. It protects you and can also help you qualify for better rates.
Expert Insights on Insuring Luxury Sports Sedans
We spoke with several insurance agents who specialize in luxury vehicles. Here is what they had to say about covering a Maserati Ghibli.
“The biggest mistake Ghibli owners make is not understanding their coverage,” says one specialist. “They assume all policies are the same. But luxury cars need special attention. The right coverage can mean the difference between a minor inconvenience and a financial disaster.”
Another expert adds that working with an agent who knows luxury cars makes a big difference. “Standard agents sometimes do not understand the unique needs of high-end vehicles. A specialist will know which coverages matter most and where you can save.”
Both experts agree that the Maserati Ghibli insurance cost is manageable if you take the right approach. Shop around, understand your coverage, and do not be afraid to ask questions.
Key Takeaways
- Maserati Ghibli insurance cost runs higher than average due to expensive parts, theft risk, and performance factors.
- Your age, driving record, location, and credit score all influence your premium significantly.
- Full coverage including liability, collision, comprehensive, and gap insurance is recommended for Ghibli owners.
- Shopping around and comparing quotes is the best way to find affordable rates.
- Bundling policies, increasing deductibles, and asking for discounts can all lower your premium.
- Common mistakes like choosing minimum coverage or not updating your policy can lead to costly problems.
- Working with a luxury car insurance specialist can help you navigate the process with confidence.
Conclusion
The Maserati Ghibli insurance cost is something every owner or prospective buyer needs to understand. It is not just about the sticker price of the car. Insurance is a ongoing cost that comes with the territory of owning a luxury sports sedan.
The good news is that you have more control over your rates than you might think. By understanding the factors that drive the cost, choosing the right coverage, and following the tips in this guide, you can find a policy that fits your budget and protects your investment.
Do not let the high cost of insurance scare you away from the Ghibli. With the right approach, you can enjoy this beautiful car without worrying about breaking the bank on coverage. Start shopping for quotes today, and take the first step toward smart, affordable Maserati Ghibli insurance.
FAQs
Is the Maserati Ghibli expensive to insure?
Yes, the Ghibli is more expensive to insure than most sedans. Luxury cars have higher repair costs, more theft risk, and a performance profile that insurers see as higher risk. On average, full coverage runs between $2,000 and $4,500 per year.
What is the cheapest way to insure a Maserati Ghibli?
The cheapest way is to shop around and compare quotes from multiple insurers. You can also lower your premium by bundling policies, increasing your deductible, maintaining a clean driving record, and asking for all available discounts.
Does the Ghibli trim level affect insurance rates?
Yes, it does. Higher trims like the Ghibli S and Ghibli Trofeo have more powerful engines and more features, which means higher insurance costs. The base Ghibli will generally be cheaper to insure than the top-tier trims.
Do I need full coverage for a Maserati Ghibli?
Full coverage is highly recommended for a Ghibli. The cost of repairs and replacements is very high, and minimum liability coverage alone will not be enough to protect you financially in a serious accident.
Can I lower my Maserati Ghibli insurance cost over time?
Yes, you can. Maintaining a clean driving record, taking a defensive driving course, installing anti-theft devices, and reducing your annual mileage can all help lower your premiums over time.
How often should I compare Maserati Ghibli insurance quotes?
You should compare quotes at least once a year, ideally before your policy renewal. Insurance rates change frequently, and a company that was competitive last year may not be the best option this year. Regular comparison ensures you always get the best rate.